Barndominium Financing: Your Options, and How Building Financing Fits In
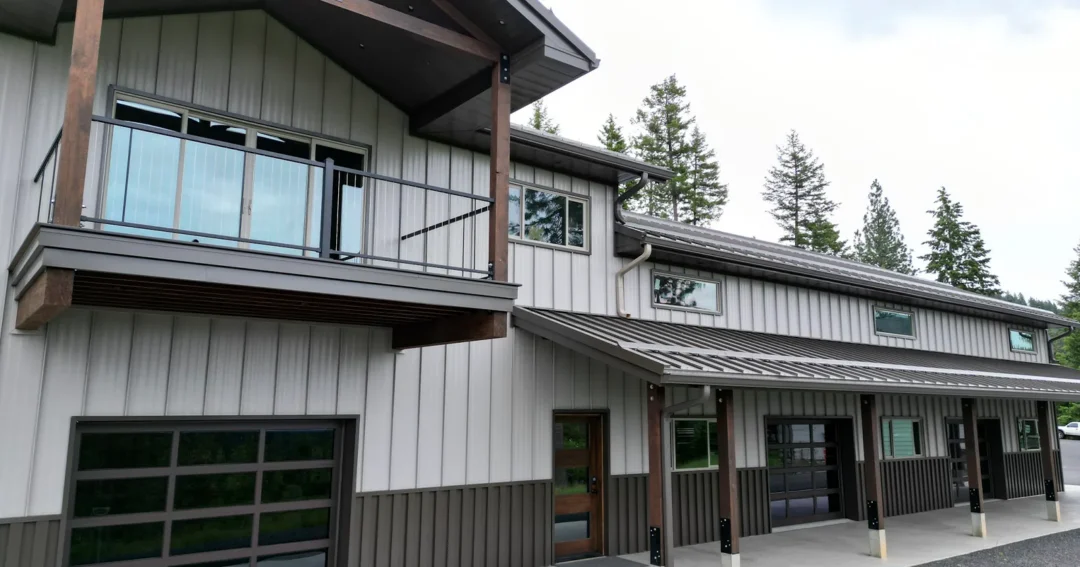
Barndominium financing can feel harder than financing a regular house, mostly because a barndominium doesn’t fit neatly into one lender box. Is it a home, a shop, or a steel building? The honest answer is that it’s often all three, and the right loan depends on how much of the building is living space, what you already own, and how big the project is.
Here’s a plain-English look at the main ways people pay for a barndominium, where each one fits, and how Steel Structures America’s building financing works alongside them.
Why Barndominium Financing Works Differently
Most home loans assume a conventional stick-built house with plenty of similar homes nearby to compare it to. A barndominium is a post-frame steel building with living space inside, and in some rural areas there aren’t many recent barndominium sales for an appraiser to use as comparables. That can make some lenders cautious, and it’s why it pays to talk to lenders who’ve financed post-frame homes before.
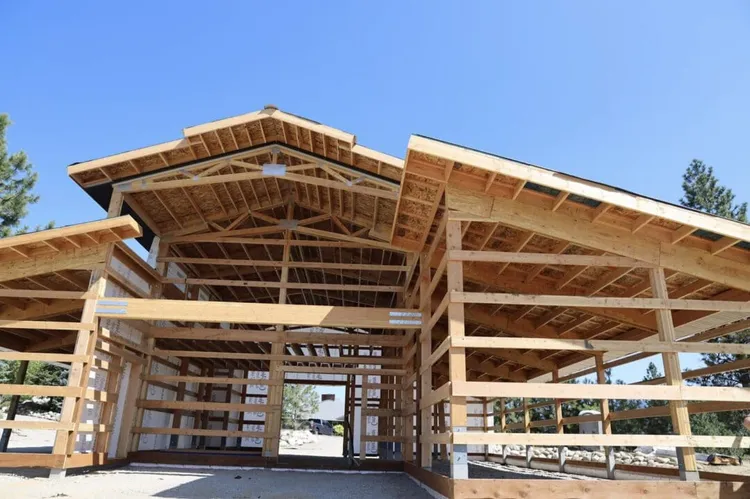
The other wrinkle is that you’re usually financing construction, not buying something that already exists. That means the money has to be available in stages while the building goes up, not in one check at closing.
Common Barndominium Financing Options
Construction loans and construction-to-permanent loans
A construction loan pays out in draws as the build progresses. A construction-to-permanent loan rolls that into a regular mortgage once the home is finished, so you close once instead of twice. This is the most common path when the barndominium will be your primary home and the living space is fully finished. Our article on construction loans vs. personal loans walks through how the two compare.
Home equity, HELOCs, and refinancing
If you already own a home with equity, a home equity loan, a HELOC, or a cash-out refinance can fund some or all of the build. The tradeoff is that you’re borrowing against the home you already have.
Credit-based building financing
Some programs finance the building itself based on your credit, without a new mortgage. This is what Steel Structures America offers, and it’s covered in the next section.
Land loans
If you don’t own the land yet, that’s usually its own loan or purchase, separate from the building. Our barndominium planning checklist covers what to settle about your land before you start.
How Steel Structures America Financing Fits a Barndominium
Steel Structures America facilitates credit-based financing for the building. Here’s how the program works, per our financing page:
-
It isn’t a mortgage. Approval is based on credit and debt-to-income ratio, and the financed structure secures the loan through a UCC-1 filing instead of a mortgage on your home or land.
-
Loans up to $250,000. $0 down through $100,000. Above $100,000, it’s 15% down.
-
No appraisal needed, which sidesteps the comparable-sales problem described above.
-
Vacant land is eligible, along with primary residences, vacation homes, and investment or rental properties.
-
Terms up to 144 months, with no prepayment penalty.
-
A same-day or next-day decision is typical once the application is complete.
Rates depend on your credit range and the term you choose, and they’re subject to change, so check the Steel Structures America financing page for current rates, the payment estimator, and the full disclosures.
When a project is bigger than $250,000
A fully finished barndominium home can run past the program’s maximum. For larger projects, the financing page notes that alternatives may be available, including HELOCs, lines of credit, first or second mortgages, and refinances. A financing specialist can help you figure out which path fits your project.
How to Get Ready for Barndominium Financing
-
Get a real quote first. Every lender wants to know the project cost. With SSA, the first step is talking with a project manager and getting a quote, then reviewing financing with that number in hand.
-
Know your budget for the whole project, not just the shell: site prep, concrete, utilities, and interior finish. Our barndominium cost guide breaks down what moves the number.
-
Gather income documents. For SSA’s program, wage earners provide a current paystub and the previous year’s W-2. Self-employed applicants should expect to provide two years of tax returns and a year-to-date profit-and-loss statement. The financing page lists the full checklist.
-
Decide how finished it’ll be. A barndominium you’ll finish over time may finance differently than a move-in-ready home.
FAQ
Can you get a regular mortgage on a barndominium?
Often, yes, once it’s a finished home that meets the lender’s requirements. Construction-to-permanent loans are a common way to get there. Ask lenders whether they’ve financed post-frame or barndominium homes in your county.
Does Steel Structures America financing require home equity?
No. It’s credit-based and secured by the financed structure, so your home equity stays available. See the financing page for eligibility details.
Is barndominium financing different from shop or pole barn financing?
The building financing works the same way for a barndominium, shop, or barn. Where it differs is the mortgage side, since a barndominium is a home. For buildings without living space, see our guides to pole barn financing and metal building financing.
The Bottom Line
Barndominium financing usually comes down to a construction or construction-to-permanent loan, home equity, credit-based building financing, or a mix. Get a real quote first, then match the loan to the project. If you’re planning a high-end build, our luxury barndominium guide shows what drives the finish level. Steel Structures America builds barndominiums across Idaho, Washington, Oregon, Montana, and Colorado. Give us a call at (800) 833-9997 or request a free quote, and ask about financing when you do.